Extended further
Extended until 7/15.
Extended to 4/15/26
Update 9/11/25: Available again. Valid until 01/21/2026
Extended to 10/15/25
Update 4/21/25: Extended to 7/16/2025
Update 1/17/25: Extended until 4/16/25
Update 10/3/24: Extended until 1/22/25
Update 7/29/24: Back until 10/16/24
Update 5/18/24: Extended through 7/24/24
Offer at a glance
- Maximum bonus amount: $3,000
- Availability: Nationwide, in-branch only
- Direct deposit required: None
- Additional requirements: Deposit $500,000 and maintain for 90 days
- Hard/soft pull: Soft
- ChexSystems: No
- Credit card funding: Cannot fund with debit or credit in branch.
- Monthly fees: None
- Early account termination fee:
Bonus taken back if closed within six monthsNone - Household limit: None listed
- Expiration date:
April 23rd, 2019 June 15th, 2019 August 6th, 2019 September 28th, 2019November 19th, 2019 October 19, 2022April 19, 2023July 24, 2024
The Offer
Direct link to offer (incognito)
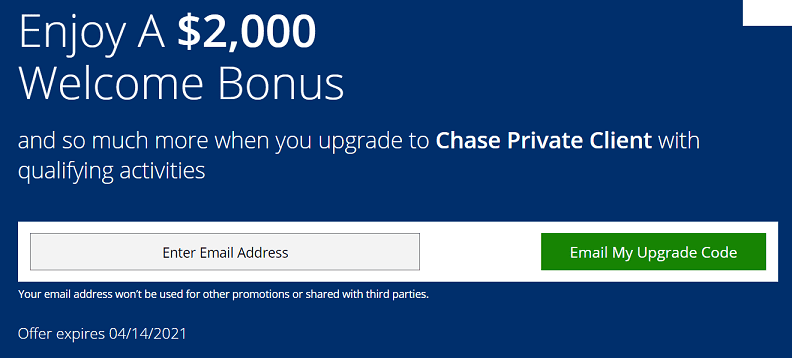
- Meet with a Private Client Banker to upgrade (or open) your Chase account to Chase Private Client and receive a bonus of up to $3,000 when you meet the following requirements:
- Within 45 days transfer a total of $500,000 or more in new money to a combination of eligible check, savings and/or eligible investment accounts (deposit $500,000 for $3,000 bonus or $250,000 for $2,000 bonus or $150,000 for $1,000 bonus).
- Maintain that balance for at least 90 days from coupon enrollment.
- Bonus will be deposited into your account within 40 days.
The Fine Print
- Offer not available to existing Chase Private Client customers.
- To receive the $1,250 bonus: 1) Meet with a Private Client Banker to upgrade your existing account to Chase Private Client CheckingSM account. 2) Within 45 calendar days, transfer a total of $250,000 or more in qualifying new money or securities to an eligible checking, savings and/or J.P. Morgan investment accounts (opened in a Chase branch and serviced by a J.P. Morgan Private Client Advisor or Financial Advisor).
- Ineligible accounts: any You InvestSM accounts, Certificates of Deposit, insurance products; fixed and variable annuities; 529 College Savings Plans; any retirement accounts such as Traditional and Roth IRAs, Keogh, Simple IRAs, and 401(k) Plans.
- The qualifying new money or securities must be transferred from non-Chase or J.P. Morgan accounts and cannot be funds or securities held by Chase or its affiliates. AND 3) Maintain at least a $250,000 balance for at least 90 days from the date of funding (gains and losses to qualifying investment balances from trading or market fluctuation will not be counted for purposes of meeting the balance requirements).
- After you have completed all the above requirements, we will deposit the bonus in your existing Chase Private Client Checking account within 10 business days.
- The Annual Percentage Yield (APY), for Chase Private Client Checking effective as of 01/22/19 is 0.01% for all balances in all states. Interest rates are variable and subject to change. Additionally, fees may reduce earnings on the account.
- You can only participate in one Chase Private Client Checking, Sapphire Checking or You Invest new money bonus in a 12 month period.
- Coupon is good for one time use. Bonuses are considered interest and will be reported on IRS Form 1099-INT (or Form 1042-S, if applicable).
- All bank account bonuses are treated as income/interest and as such you have to pay taxes on them
Avoiding Fees
Monthly Fees
As far as I know there is no monthly fee, but if you don’t maintain the $250,000 balance requirement they might downgrade your account to something else
Early Account Termination Fee
Bonus taken back if closed within six months There is no longer any early termination fee.
Our Verdict
You could sign up for a $600 checking/savings bonus and then wait six months and then do this deal in branch. The fine print says you’re not eligible for this bonus if you’ve done any Sapphire Checking, Chase Private Client Checking or You Invest new money bonus in a 12 month period, rather than every two years on the regular Chase checking/savings bonus.
For most people this $2,000 Chase Private Client bonus isn’t worth considering because YouInvest balances do not qualify and Chase deposit accounts earn a very low APR and the other investment accounts have higher fees than other options. Because of that I wouldn’t recommend signing up for this deal.
Useful posts regarding bank bonuses:
- A Beginners Guide To Bank Account Bonuses
- Bank Account Quick Reference Table (Spreadsheet) (very useful for sorting bonuses by different parameters)
- PSA: Don’t Call The Bank
- Introduction To ChexSystems
- Banks & Credit Unions That Are ChexSystems Inquiry Sensitive
- What Banks & Credit Unions Do/Don’t Pull ChexSystems?
- How To Use Our Direct Deposit Page For Bank Bonuses Page
- Common Bank Bonus Misconceptions + Why You Should Give Them A Go
- How Many Bank Accounts Can I Safely Open Within A Year For Bank Bonus Purposes?
- Affiliate Links & Bank Bonuses – We Won’t Be Using Them
- Complete List Of Ways To Close Bank Accounts At Each Bank
- Banks That Allow/Don’t Allow Out Of State Checking Applications
- Bank Bonus Posting Times
Post history:
- Update 1/16/24: Extended to 04/17
- Update 10/6/23: Extended to 01/24/2024.
- Update 7/23/23: Extended until 10/18/2023.
- Update 2/21/23: At some point the terms changed slightly so that you only need to have the funds in the account from day 45 through day 90. There has also been some discussion in the comments about using J.P. Morgan investing without paying fees. And so there might be ways for this offer to make sense.
- Update 2/20/23
: There’s a new link(open incognito) with a tiered deposit requirement – $1,000 bonus with $150,000; $2,000 bonus with $250,000; $3,000 bonus with $500,000. Still none of these are very interesting IMO given the loss of interest on the funds. - Update 1/13/23: Offer extended to 4/19/23.
- Update 10/15/22: Offer extended to 1/25/23
- Update 8/15/22: Deal is back at this link (incognito) and valid through 10/19/22. The fine print indicates it works for new Chase checking customers or existing checking customers who upgrade or existing Private Clients who make a $250,000 deposit. Requires Chase branch visit.
- Update 1/18/21: Deal is back, but has been reduced to $2,000. Valid until 4/14/21.
- Update 11/22/20: Deal has been increased to a maximum $3,000 bonus. Hat tip to reader EW
- Update 9/27/20: Deal extended until 11/23/20.
- Update 8/10/20: Extended until 10/1/20.
- Update 5/26/20: Deal might be better than we originally thought. Normally there is a 1.25% fee, YouInvest doesn’t have this fee but is excluded from counting for this bonus. They have another self directed account called “Full Service“, this has no management fee if your a Chase Private Client (CPC). There is an annual fee of $50, but this is waived if you are CPC or have $25,000 in investments.
- Update 5/25/20: Deal is back and valid until 8/10/20. Hat tip to reader Don
- Update 1/19/20: Deal has been extended until March 6th, 2020.
- Update 11/20/19: Bonus has been extended until January 17th, 2020.
- Update 11/8/19: Bonus has been increased to $2,000 (up from $1,250).
- Update 8/15/19: Deal has been extended until September 28th, 2019. Hat tip to MtM
- Update 6/17/19: Deal has been extended until August 6th, 2019.
- Update 4/24/19: Deal has been extended until June 15th, 2019.

Sue , I am not sure that I understand your question. So far I have only had the managed investment account and I have churned that with my CPC account(s); The investment account is a joint account, so P2 has also been able to use it to churn P2’s separate CPC account(s).
Erik Hi Erik! I was wondering if you were able to churn the CPC offer with an Investments Direct account for accounts that fell under $100k? I recently got a notice that my account is being converted to Investments Direct.
$3000 bonus is for $500k moved to Chase. There are lower tiers, $1k for $150k, $2k for $250k. They require a managed account for the bonus, years ago used to be able to do self direct.
I never understand how to do this CPC deal, can someone please explain? Last time I checked Chase told me I can’t have the bonus of $3000 if I transfer the money to self manage brokerage account, and it needs to be advisor managed and needs to charge a fee and it need to transfer $500k. Is that app true??
Going for a bit of an experiment. Doing this bonus for the 3rd or 4th time. I still have an old no-fee brokerage account opened by an advisor, that was kept open with $0 balance for the last year+ after transferring out assets last after the last time I got one of these bonuses. The advisor is no longer assigned to the account. I saw talk of accounts being converted to another account type, but I checked and my most recent statement looks exactly the same as in the past when advisor was assigned, so I hope this is a good indicator that it’s still of the eligible account type. I still have about 2 months of holding assets and then the wait period for bonus posting so it won’t be until close to end of year when I get the bonus, if I do. Will definitely follow up here when I get the bonus (or if I don’t…).
In case anyone else has this issue, my tax lots for my mutual fund do NOT show up on the web interface (shows average cost basis) but DO show up correctly on the PDF statement.
Thanks! Will keep an eye out. Can always send a brief email when they call
Yes, search for “convert” or “transition” in the comments here. Though, someone was able to call and cancel the conversion.
Oh wow. They can change the account type while it has assets in it?
Previous data point suggest your advisor may drop you and change your full service account to self direct investment account.
Once CPC bonus enrolled and JPM non AUM account is open, assets are transferred, do you have to keep meeting with the advisor? If you don’t continue to play along, can they unilaterally close your account?
Wonderful, thanks for reporting back. I just cancelled CPC last week. Going to wait 90 days to apply for CTC in branch. You’d probably did see the tracker on your accounts during the qualification period which confirms it’s tracking as expected.
Kevin I did end up getting the CTC bonus and posted the DP here #2371856 . I should have updated here as well. There’s always a risk that Chase will start adhering to those terms. I went in-branch this time to open the Total Checking account (maybe to get some reassurance from the banker?), but I wonder if online would be better because I think I recall some saying that it won’t let you apply if you aren’t eligible for the offer. Also tagging RM Ricki Jay
catcat
CatCat since it’s been more than 100+ days, were you paid out for CTC bonus? What was your experience? Thanks
A fellow poster over at Bogleheads shared this large disclosure document. https://www.chase.com/content/dam/chase-ux/documents/personal/investments/jpm-investment-account-agreements.pdf It notes the $500 minimum to avoid closure on page 17 — “f. Low balance accounts. If your Brokerage Account falls below $500 in value, you authorize JPMS, in its discretion, to liquidate your securities and close your Brokerage Account.”
That sounds super awkward. Did you, your wife, or banker say anything about it?
Just downgrade your client to the total checking after getting the bonus or you can keep the checking account at private client and move in the necessary amount of new assets.
Appears to be extended through mid-October, if you request a code now.
We left self-directed JPM brokerage accounts open ($1 balance or something) over the past year, so luckily no advisor this year, salivating over our assets. Last year we had to meet with advisor to open up self-directed account, which he did begrudgingly for us (since he earns no AUM for it). I wish Chase Private Client & Wells bonuses didn’t require in-branch visit. Would be so much cleaner of a churn. But for $9k/year, I’ll stomach the awkwardness. We should probably stagger our account openings to increase the bonus size (shuffle $500k of mutual funds from P1 WF to P2 WF to P1 jpm chase to P2 jpm chase), but so far haven’t optimized that much yet. Would net us another $2k/yr on the Chase side vs $250k. Anyone else sloshing assets (e.g. mutual funds) from one spouse to another to maximize bonuses? It’s double the bonus fun.
sg77 Right, agreed. The notice I received only mentioned closure, nothing about fees
The $500 minimum to avoid the account being closed might be unrelated to what’s needed to avoid being charged a fee.
Bob Curious if you are opening new brokerage accounts, as well, or left them open from your previous churn? In my experience, the advisor is assigned by branch location so where you opened the CPC checking would determine where/who your JPMS advisor is. For example, during my second churn I went to another branch to open new accounts (I had closed both checking and brokerage from another branch the previous year). The advisor at this new branch had to ask my previous advisor to relinquish/release my closed brokerage before the new advisor could be linked to it. I wouldn’t worry about any awkwardness about opening new accounts with the checking accounts. They’re still earning commission 🙂
About 13 months after churning our last CPC bonus, my wife and I opened up CPC accounts (x2) again this past week — with the same banker — the awkwardness was palpable. I should have driven an extra 20 minutes to another branch. For the veteran churners here, how do you deal with this issue? Broadly, are we at risk of being blacklisted if we churn annually? I love this bonus, combined with WF (x2).
Finally got my conversion to the team of advisors (phone-based) notice. More than 2 years after having any significant amount of assets. No mention of minimum, but just a general reference that product access differs from a CPC advisor.
Bonus posted for my legacy full-service brokerage account.
Do you have to open up a new Chase private client brokerage account every year to get the bonus or can you just transfer new funds each year?
Thanks for checking. Pricing still says $25k, but I suppose an FI can always be cheaper than disclosed! Hopefully they keep everyone as full-service even with $500. I haven’t gotten a letter yet. “ANNUAL ACCOUNT FEES Brokerage Account $50 — How to avoid this fee: Be a Chase Private Client or have $25,000+ in combined investment balances or generate $50 in commissions in your account during a calendar year”
An email from Chase Private Client outlining my next steps to earn the bonus confirms that my hold period ends 45 days, not 90 days, after then the end of the 45-day funding period. Evidently Chase believes a 45-day hold period is appropriate or else they wouldn’t have made the offer, would they. I didn’t argue with an investment advisor about the hold period of the bonus offer. I haven’t even met him. The terms of the bonus offer are of no interest to an investment advisor. I argued with the Chase Private Client banker only after he insisted the hold period was 90 days. Furthermore, just because the hold period ends doesn’t necessarily mean that I will withdraw all of my funds. In any case, the CPC bank wouldn’t be managing my money anyway. (You should have heard the pathetic sales pitch he gave for keeping my money with Chase, after he admitted that Chase pays only 0.01% interest on its checking and savings accounts.) I got another call from the Executive Team rep I spoke with a couple days ago. He agreed with me that the CPC banker and his manager had acted inappropriately; that you don’t turn away a customer who’s bringing in a quarter million; that goodwill in the short term can lead to a longer-term relationship; that there’s no limit on how many Chase investment advisors I may interview; and that I am free to open a Chase investment account with any advisor at ANY branch in ANY state, even over the phone. The Executive Team rep had a talk with the CPC banker’s manager. As a result, a meeting has been re-scheduled for me to meet with the investment adviser that the CPC banker had originally told me would open the type of account I want, then arbitrarily canceled the meeting he had scheduled, refused to give me my offer enrollment confirmation receipt, and stated that he was going to disenroll me from the bonus offer. Going forward that CPC banker will not to be involved. Yes, Chase doesn’t have to open an account for me. But whether a Chase investment account is opened for me is not up to the CPC banker or his manager. Furthermore, the investment advisor’s manager is not the CPC banker’s manager. BTW, it was the CPC banker’s manager who submitted a complaint on my behalf. In my experience, submitting complaints in banking disputes always gets me where I want to be.
This bonus might not be for you…the play is to show interest in their services without getting stuck on fees, then nudge them to open the other account, but leave the door open for help in the future. Some advisors won’t play ball. You’ll notice it early on, don’t waste your time and gracefully exit. Arguing with them about 90 day hold, which is already short, makes it obvious what you are up to and that you are difficult to work with..not surprising that they cancelled on you. Stick with what the fine print says, you will not convince them. If the rep is wrong, they’ll point to the fine print anyway. So there is zero value in getting them to agree with you. Submitting complains just gets eyes on your account and will get you nowhere. They don’t have to open an account for you, it’s weird but they clearly have that leeway.