U.S. Bank has launched two new business cards:
- U.S. Bank Business EssentialsTM Visa® Card
- U.S. Bank Business EssentialsTM Plus Visa Signature® Card
Both cards earn 2% cash back on all purchases and increased earn rates depending on your U.S. Bank business checking balance.
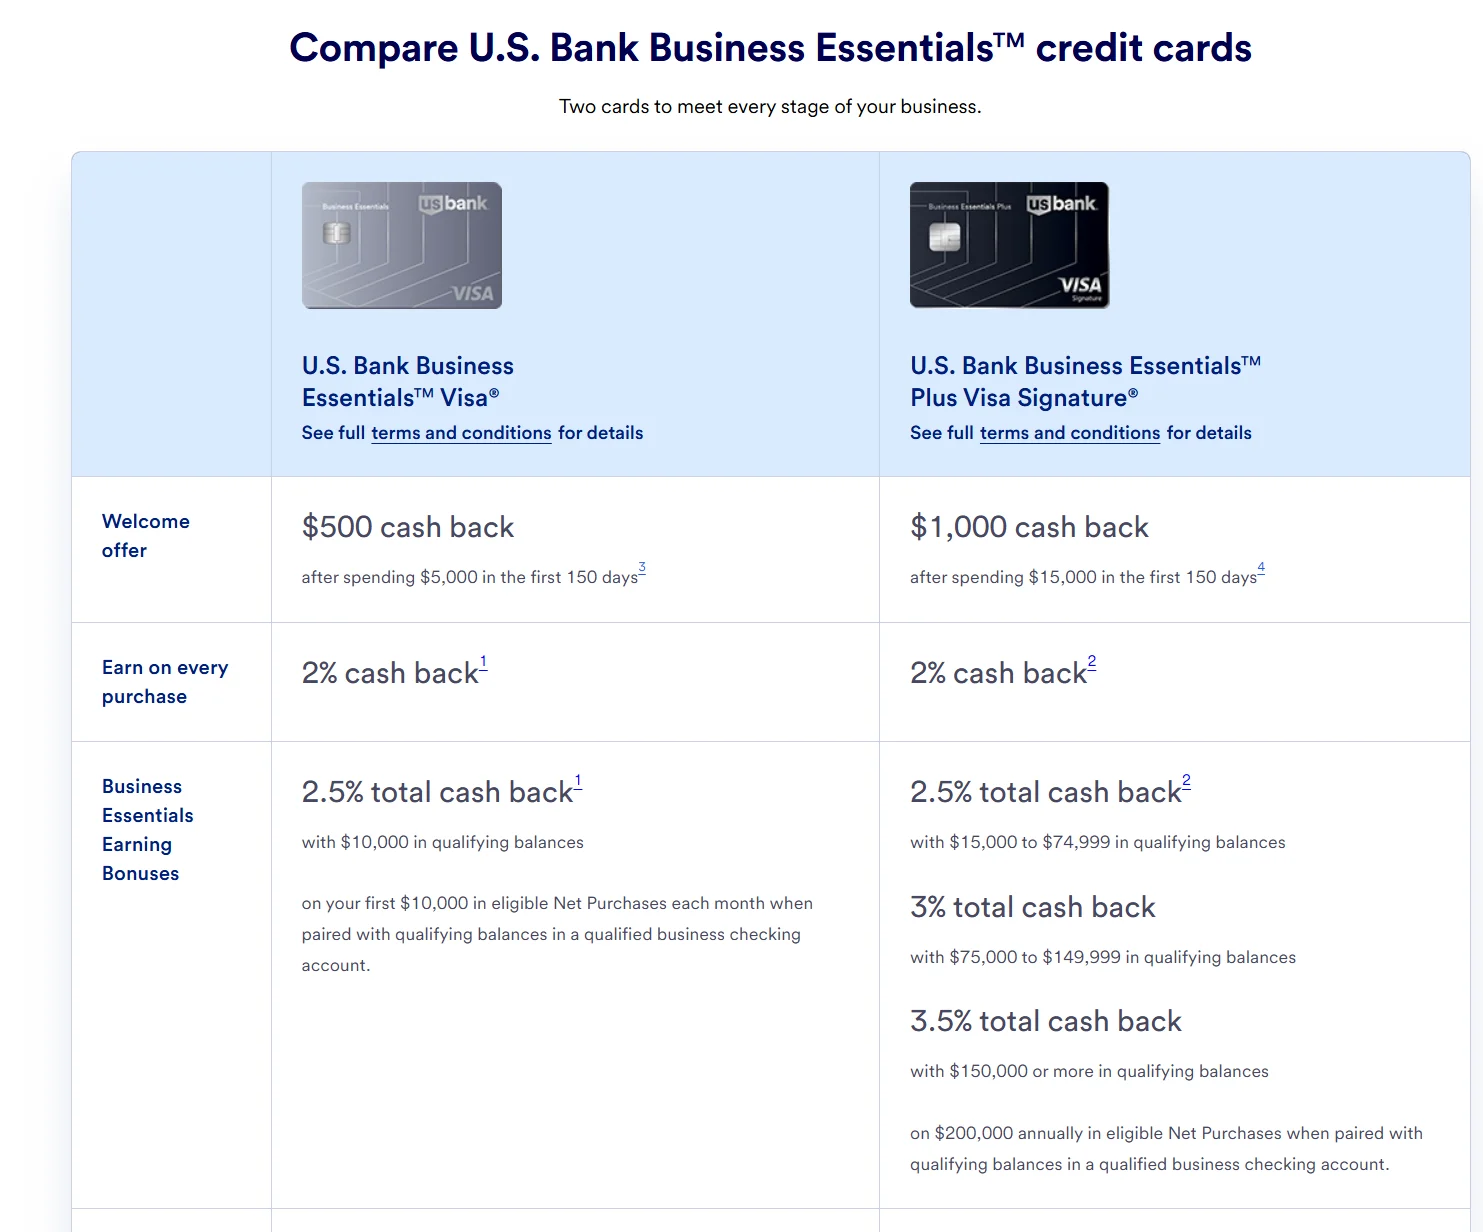
U.S. Bank Business Essentials
- No annual fee
- $500 cash back sign up bonus after you spend $5,000 within the first 150 days
- 0% APR on purchases for the first 12 months
- Card earns 2% cashback on all purchases, 2.5% if you have $10,000 in qualifying balances (on your first $10,000 in spend each month)
U.S. Bank Business Essentials Plus
- $295 annual fee
- $1,000 cash back sign up bonus after you spend $15,000 within 150 days of account opening
- Card earns at the following rates:
- 5% cash back on your top spend category, up to $200,000 annually. Eligible categories are accounting & tax services, airlines, cell phone service providers, dining, entertainment, office supply stores, postal & shipping services, and utilities
- 2% cashback on all purchases (up to 3.5% broken based on qualifying balances. Up to $200,000 in spend annually)
- 2.5% if you have $15,000-$74,999 in qualifying balances
- 3% if you have $75,000-$149,999 in qualifying balances
- 3.5% if you have $150,000 in qualifying balances
Balance Requirements
The balance requirements must be in one of the following eligible accounts:
- U.S. Bank Business Essentials®
- U.S. Bank Gold Business Checking
- Gold Business Checking with Interest
- U.S. Bank Platinum Business Checking
All of these accounts earn 0% or close to from what I can tell.
Our Verdict
Interesting products, main issue is that you need to tie up funds and those funds will earn 0% APY while you activate the increased earn rate. If you spent the full $200,000 and earned 3.5% this is an extra $1,000 over the Robinhood gold card that earns a flat 3%. You also need to take into the $295 annual fee and the fact that $150,000 in a 5% account even for one month would earn $625. The sign up bonus on the Essentials Plus is good but again $295 annual fee so a lot of people prefer the Triple Cash with a $750 bonus (& $100 software credit) with no annual fee. The 5% on your top category could put it over the edge for some people and I’m sure there are already some businesses that hold that amount with U.S. Bank already for whatever reason that could benefit. Also could be useful for people completing U.S. Bank business checking bonuses. For a full list of new credit cards launched this year, click here.
Hat tip to reader Tamis



I certainly agree with the general sentiment about opportunity costs of keeping money in a deposit banking account earning zero-ish APY versus an HYSA. However, interest earned from checking and savings accounts also results in a 1099-INT being issued (i.e. – generates a tax liability), which becomes more relevant when you’re talking of adding high fours or low fives in income. Conversely, cashback earned through credit card purchases generally does not, so the math isn’t quite as black and white.
I seriously thought most did. WF and Chase worked for me recently I’ve been out of that game for a while, but Citi was the only one I’ve avoided because they were CA crazy. Maybe you’re encountering certain banks that code it differently (I’m mostly using local and National Credit Unions)
Michael Patterson Points are 1:1 for cash redemption for CIC. If using the Chase ecosystem (airline or hotel transfers, travel portal) is something you do, they can be worth more than that. US Bank utilizes the point system as well. It’s more restrictive with minimums and cash out may require a checking account at US Bank.
Is this better than CIC for GCs from office since the 5X would be in cash rather than points?
If you’re considering the Plus mostly because of the higher cash back percentages, be sure to consider the opportunity cost. Having a large amount sitting at roughly 0% APY can easily outweigh the difference from keeping that cash in a high-yield savings account. For most people, the no annual fee Essentials card will be the better choice unless you happen to have this sort of cash at U.S. Bank anyway.
I currently have 4 US Bank Business cards, but under different EINs. They do
Does the plus come with phone insurance?
My bet is on 5% category of your choice options gradually shrinking to just “bowling alleys”.
No
Isn’t that what we have written?
I suspect they will have similar limitations as Smartly card.
Can you clarify which card you used that earned no points? I am unaware of any other than Amex and USAA cards.
There’s the FIGFCU Crystal Visa that pays 3% the first year and 2.5% thereafter. There’s a $99 AF that’s waived for the first year, and there’s a $100 SUB. See https://www.doctorofcredit.com/farmers-insurance-federal-credit-union-figfcu-250-checking-bonus/#comment-2420384
Maybe they figure a 21 year old won’t have the discipline to pay off every month. Presumably you’re not a profitable customer.
possible to do the $15k spend, get the $1k, and then downgrade card?
Not sure if anyone else noticed, but US Bank updated the card designs for all business cards. Even the Altitude Business card was changed. I suspect that some full refresh and design update is going to come to US Bank personal cards as well. It seems like US Bank is looking over their whole credit card portfolio, and is reformatting everything to be more competitive.
Waiting for DPs on what counts as “tax services”
Yeah, that’s what I’ve seen. My bank goofed up and did back-to-back $3K initial deposits and the second one was declined because I had a 5K cash advance limit. The downside with USBank that I’ve seen however is no points/cashback on these transactions. Still, 0% APR free money is 0% APR free money.
Accounting and tax services – wonder if that includes Pay1040.com. If so, this could be a big MM for a lot of businesses.
5% on utilities, up to $200k (Homer drool) but… -is a business card -Cash+ thing doesn’t work any more (‘cept through Elan) (sips back drool)
How many US Business cards can I have? I currently have 6 cards with them, 2 personal and 4 business (Two triple cash, a business leverage, and Platinum Card). I am currently 3/24. I want to go for the U.S. Bank Business Essentials. Can anyone help
US Bank hates me for whatever reason. I always got denied with clean profile. 800+, 3/12, 4/24.
Wish it was ‘tax payments’ and not lumped into ‘accounting and tax services’ !
…
I wish this had existed last week. I got my 2nd triple cash and considered a double application but chickened out. I would’ve gone for the double if this existed.
You can leverage the 0% APR like the triple cash to then use the money to get other bonuses or high yield. But you may just want to use the triple cash anyway. I use them for bank account funding and/or taxes and defer payment until the following year, using the liquid for those others. Its nice to have another 0% Apr Option Afaik most of the 3x points you mention dont typically have 0% APR and those points don’t redeem for cash value as nicely. Which helps pay down the any of the 0% apr balance. Or tax fees for paying with CC. The triple cash and this SUB basically pays you to pay taxes.
Yes, the metal cards do feel pretty cool. I don’t think I’d ever apply for a card just because it’s metal (of course)
Just got approved for 2nd Triple cash. Hmmm
thats crazy
i unironically think thats pretty cool